Delaware beach property insurance is a specialized policy protecting coastal homes from storm damage, flooding, and liability risks. Standard homeowner policies often exclude water damage, leaving owners exposed. Crowley Real Estate Associates Inc. advises buyers to secure comprehensive coverage before closing to protect their investment in the Delaware shore.
Standard Homeowner Policies vs. Coastal Risks
Most standard homeowner policies exclude flood damage and windstorm losses in high-risk coastal zones. Delaware's shoreline faces unique exposure to Atlantic storms and rising tides. A standard policy is a contract covering perils like fire and theft, but it rarely includes water intrusion from outside the home. Buyers must understand that "all-risk" language in standard policies often contains specific exclusions for named perils like hurricanes.
For properties in Bethany Beach or Rehoboth Beach, the gap between standard coverage and actual risk is significant. The implication is that relying solely on a basic policy can result in catastrophic out-of-pocket costs after a storm event. Owners should review their declarations page carefully to identify excluded perils.
The Critical Role of Flood Insurance
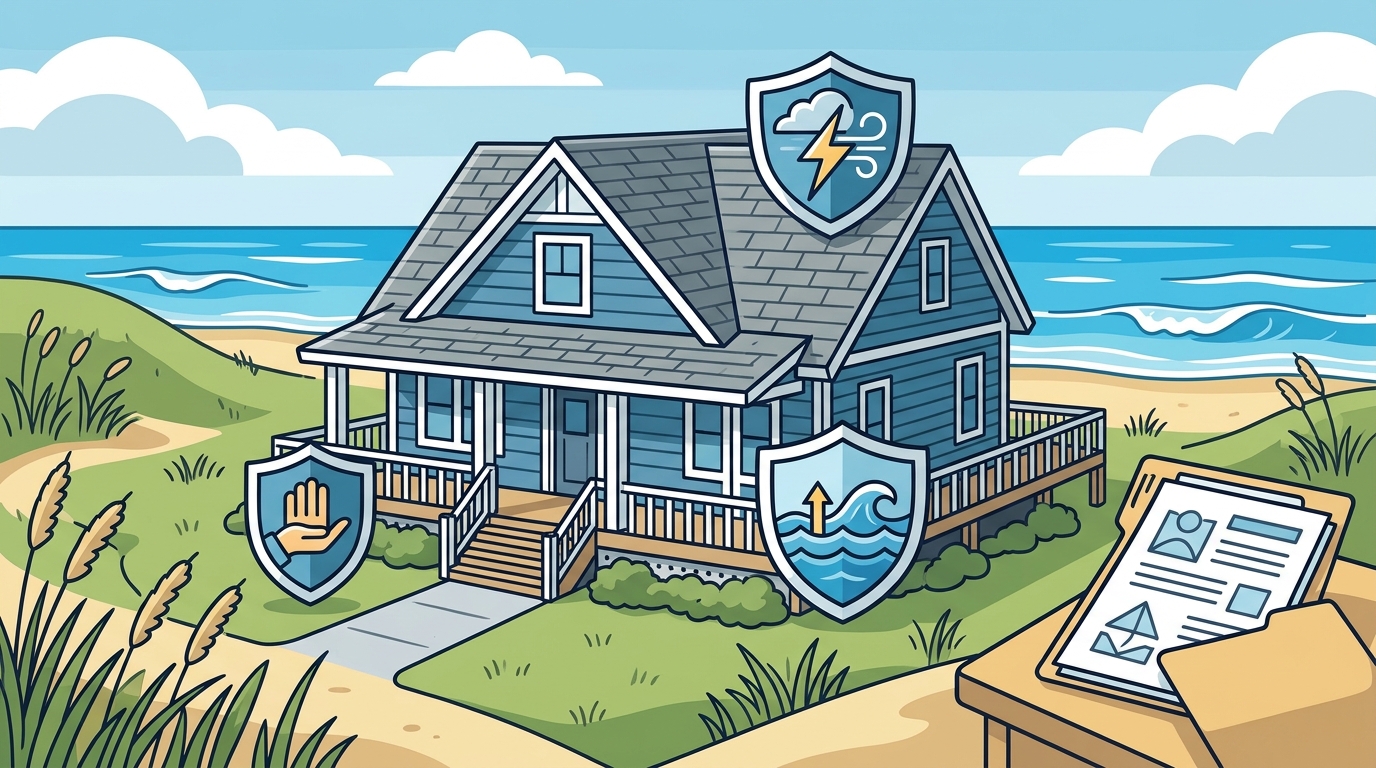
Flood insurance is a separate policy required for properties in designated Special Flood Hazard Areas (SFHAs). The National Flood Insurance Program (NFIP) is the primary provider of this coverage in Delaware. If a lender requires it, the policy is mandatory; if not, it is still highly recommended for coastal properties. Flood insurance is a financial safety net covering water damage from rising water, not wind-driven rain.
Properties located within two blocks of the beach, such as those in the Ocean Block of Bethany Beach, are prime candidates for flood coverage. The evidence shows that wind-driven rain is covered under wind policies, but standing water is not. Owners must determine their property's flood zone status to price this coverage accurately.
Wind, Hail, and Named Storm Coverage
Wind and hail coverage is a critical component of coastal property insurance, often requiring specific endorsements. In Delaware, wind coverage may be excluded from standard policies or capped at a low limit. Named storm coverage is a specific provision that addresses damage from hurricanes and tropical storms. This coverage is a contractual agreement to repair roof, siding, and window damage caused by high winds.
For homes in Fenwick Island or South Bethany, wind exposure is a constant consideration. The implication is that a standard policy limit may be insufficient to rebuild a beach home to code after a major storm. Buyers should ensure their dwelling coverage reflects current replacement costs, not just market value.
Liability Protection and Umbrella Policies
Personal liability coverage is a standard part of homeowner insurance, protecting owners from lawsuits if a guest is injured on the property. An umbrella policy is an additional layer of liability coverage that kicks in after the underlying homeowner policy limit is exhausted. This extra protection is a financial shield against severe injury claims or property damage lawsuits.
Vacation Rental Insurance Requirements
Vacation rental insurance is a specialized policy that covers properties used for short-term lodging. Standard homeowner policies often exclude or limit coverage for properties rented out to the public. This specialized coverage is a business-oriented policy that addresses risks associated with transient guests, such as theft, damage, and liability. Crowley Real Estate Associates Inc. manages numerous vacation rentals and emphasizes the need for proper insurance classification.
Owners listing properties in communities like Bethany Village or Rehoboth Beach must ensure their insurer knows the property is used for rentals. The implication is that failing to disclose rental use can lead to claim denials. Owners should consult with their agent to adjust their policy to reflect the rental income and usage patterns.
Key Takeaways
- Standard homeowner policies often exclude flood and wind damage in coastal Delaware.
- Flood insurance is a separate policy required for properties in designated flood zones.
- Wind and hail coverage may need specific endorsements to be adequate for beach homes.
- Umbrella policies provide an extra layer of liability protection for high-value properties.
- Vacation rentals require specialized insurance that covers short-term guest risks.
- Always disclose rental use to your insurer to avoid claim denials.
- Review policy exclusions carefully, especially for named perils like hurricanes.
Frequently Asked Questions
Does standard homeowner insurance cover flood damage in Delaware?
No, standard homeowner policies typically exclude flood damage. You need a separate flood insurance policy, often through the NFIP, to cover water damage from rising water.
Is flood insurance mandatory for all Delaware beach properties?
Flood insurance is mandatory if your property is in a Special Flood Hazard Area and you have a mortgage. It is highly recommended for all coastal properties, even if not required by a lender.
What is the difference between wind and flood coverage?
Wind coverage repairs damage from high winds, such as roof and siding. Flood coverage repairs damage from rising water. Wind-driven rain is covered under wind policies, but standing water is not.
Do I need special insurance if I rent out my beach house?
Yes, standard homeowner policies often exclude or limit coverage for rental properties. You should obtain a vacation rental insurance policy that covers risks associated with short-term guests.
How much liability coverage should I have for a beach property?
Where can I find a real estate agent who understands insurance needs?
Crowley Real Estate Associates Inc. works with clients to understand the specific insurance requirements for properties in Bethany Beach, Rehoboth Beach, and Fenwick Island. You can contact our sales team for guidance.
Protecting Your Delaware Shore Investment
Securing the right insurance coverage is a critical step in protecting your Delaware beach property. By understanding the gaps in standard policies and obtaining specialized coverage for flood, wind, and liability, you can safeguard your investment. Crowley Real Estate Associates Inc. is committed to helping you navigate these complexities as you buy or sell on the Delaware shore. To discuss your insurance needs with a local expert, reach out to our team today.